Bankruptcy
Chicago Chapter 7 Bankruptcy Lawyers
A Complete Guide to Chapter 7 Bankruptcy in Illinois: What You Need to Know Before Filing
Financial stress can impact every part of your life. Your health, your job, your relationships, and even your sense of stability. When debt becomes overwhelming and there is no realistic path to catch up, many people begin researching bankruptcy as a way to regain financial control.
Your attorneys
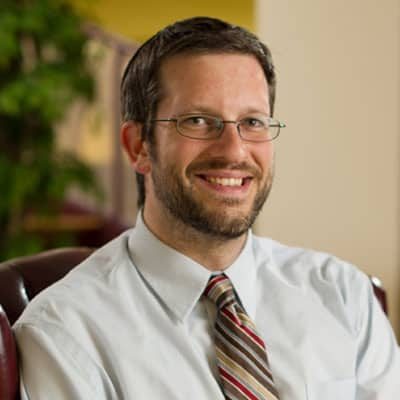
Ben L. Schneider
One of the principal bankruptcy attorneys
He focuses on individual Chapter 7 and Chapter 13 filings as well as Small Business Chapter 7 and Small Business Chapter 11 Bankruptcy filings.
- Avvo Clients’ Choice Award 2012
Matthew (Motty) Stone
Principal estate planning, business and corporate attorney
He focuses on contract review and negotiation as well as employment issues, business litigation, intellectual property, Chapter 7 and Chapter 11 Bankruptcy.
Debts that cannot be discharged
Some debts are not eliminated in Chapter 7, such as:
- Child support and alimony
- Recent income taxes
- Student loans (except in rare cases requiring an adversary proceeding)
- Criminal fines and restitution
- Debts involving fraud
Understanding what will and won't be discharged is critical, which is why most Illinois residents benefit from consulting with a bankruptcy attorney before filing.
Who qualifies for Chapter 7 bankruptcy in Illinois?
To file Chapter 7 bankruptcy in Illinois, you must meet income requirements through the Means Test, a calculation comparing your household income to the state median.
Step 1: Compare your income to the Illinois median
The first step is straightforward: if your income for the past six months is below the Illinois median for your household size, you automatically qualify. Median income amounts are updated regularly, but the general rule is:
- Lower than median = you qualify
- Higher than median = you must complete Part 2 of the Means Test
Step 2: Calculate your disposable income
Even if your income is above the median, you may still qualify after deducting allowable expenses such as:
- Mortgage or rent
- Utilities
- Car loans and insurance
- Healthcare costs
- Childcare
- Taxes
- Certain IRS-approved living expenses
If the calculation shows that you do not have meaningful disposable income, you qualify for Chapter 7.
Who doesn't qualify?
You may not qualify for Chapter 7 if:
- You have too much disposable income
- You filed Chapter 7 less than eight years ago
- The court believes you are abusing the bankruptcy system
In these cases, Chapter 13 bankruptcy may be a better option.
The Illinois Chapter 7 bankruptcy process
Most Illinois Chapter 7 cases follow the same general timeline. Understanding the process can help reduce stress and uncertainty.
Required credit counseling
Before filing your case, Illinois law, following federal requirements, requires you to complete a credit counseling course from an approved agency. This course is straightforward, takes about 60 to 90 minutes, and can be completed online.
Filing your bankruptcy petition
Your attorney will prepare your bankruptcy forms and schedules known as the petition listing:
- All creditors
- All assets
- All income sources
- All monthly expenses
- Your financial history
Once the filing fee is paid and your petition is filed with the Federal U.S. Bankruptcy Court, something important happens.
The automatic stay
The automatic stay is one of the most powerful protections in bankruptcy law. It immediately stops:
- Lawsuits
- Garnishments
- Foreclosures
- Repossessions
- Collection calls
- Debt collection letters
- Bank account freezes
If a creditor continues to contact you after your filing, they may be violating federal law.
Appointment of a bankruptcy trustee
The court assigns a bankruptcy trustee to oversee your case. The trustee's job is to review your petition, identify any non-exempt assets, and determine if any assets can be sold to pay creditors. In Illinois, most Chapter 7 cases are no-asset cases, meaning the trustee does not sell any of your property.
The 341 meeting (meeting of creditors)
About 30 days after filing, you attend a short meeting, usually 5 to 10 minutes, with the trustee. Creditors rarely attend. At the meeting, the trustee will ask simple questions, such as:
- Have you listed all your assets?
- Have you listed all your debts?
- Have you transferred anything recently?
- Are these documents accurate?
As long as your paperwork is correct, this meeting is quick and uneventful.
Debtor education course
Before receiving your discharge, you must take a second course called the Financial Management Course. Like the first course, it can be completed online.
Discharge of your debts
About 60 days after the 341 Meeting, the court enters your discharge order. This permanently eliminates all dischargeable debts and legally prevents creditors from attempting to collect them in the future. This marks the end of your case and the beginning of your financial fresh start.
Understanding Illinois bankruptcy exemptions
One of the biggest concerns people have is whether they will lose their property.
The Illinois homestead exemption
$50,000
Illinois allows you to protect:
Up to $50,000 of equity in your primary residence
Up to $100,000 for a married couple filing jointly
If your equity is below this amount, your home is protected.
Vehicle exemption
$3,600
Illinois protects:
Up to $3,600 of equity in one motor vehicle
Married couples may exempt two vehicles if titled separately
If your vehicle is financed, your equity is often far lower than your car's value.
The Illinois wildcard exemption
$4,000
Illinois provides a $4,000 wildcard exemption that can be applied to any property, including:
Cash, bank accounts, tax refunds, jewelry, other valuables
There is also a $1,000 exemption to be applied to money in a bank account in addition to the $4,000 mentioned above.
Tools of the trade
$2,250
You may exempt up to $2,250 in tools, equipment, or professional items needed for your work.
Retirement accounts
Most retirement savings
Most retirement savings, including 401(k)s and IRAs, are fully protected under Illinois law.
Personal property exemptions
Everyday items
Illinois allows exemptions for:
Clothing, household goods, furniture, appliances, books, family pictures, medical devices
These items are generally valued at garage-sale prices, meaning most household items are fully protected.
What happens to secured debts like cars and houses?
Secured debts are treated differently because the creditor has a lien on the property.
If you want to keep your car or home
You typically have three options:
- Reaffirm the loan with a reaffirmation agreement (continue payments under the same agreement)
- Redeem the property (pay the value of the property in a lump sum)
- Continue paying without reaffirmation (depending on the lender)
If you want to surrender the property
Chapter 7 allows you to:
- Surrender the property
- Wipe out the balance
- Wipe out any deficiency
This is useful for people who are upside down on a mortgage or vehicle loan.
Is Chapter 7 bankruptcy right for you?
You may be a strong candidate if:
- You have mostly unsecured debt
- You struggle to pay all monthly bills
- Creditors are suing you
- You are facing garnishment
- Your income is below the Illinois median
- You do not have significant non-exempt assets
- You want a quick resolution
- You want a fresh start
An experienced Illinois bankruptcy attorney can help you analyze your financial situation and determine whether Chapter 7 is the best solution.
Bankruptcy is not a moral failure. It is a legal tool designed to help honest individuals regain financial stability.
Getting a fresh start through Chapter 7 bankruptcy in Illinois
If you are overwhelmed by debt, you're not alone.
Filing Chapter 7 bankruptcy in Illinois can:
- Stop collections instantly
- Protect your property
- Eliminate most debts
- Help you rebuild your financial life
Contact one of our bankruptcy lawyers for a free consultation.
Schedule a free consultation
Call to set up an appointment or simply fill out the contact form to schedule a virtual consultation or an in person consultation at any of our Chicagoland locations.
847-933-0300